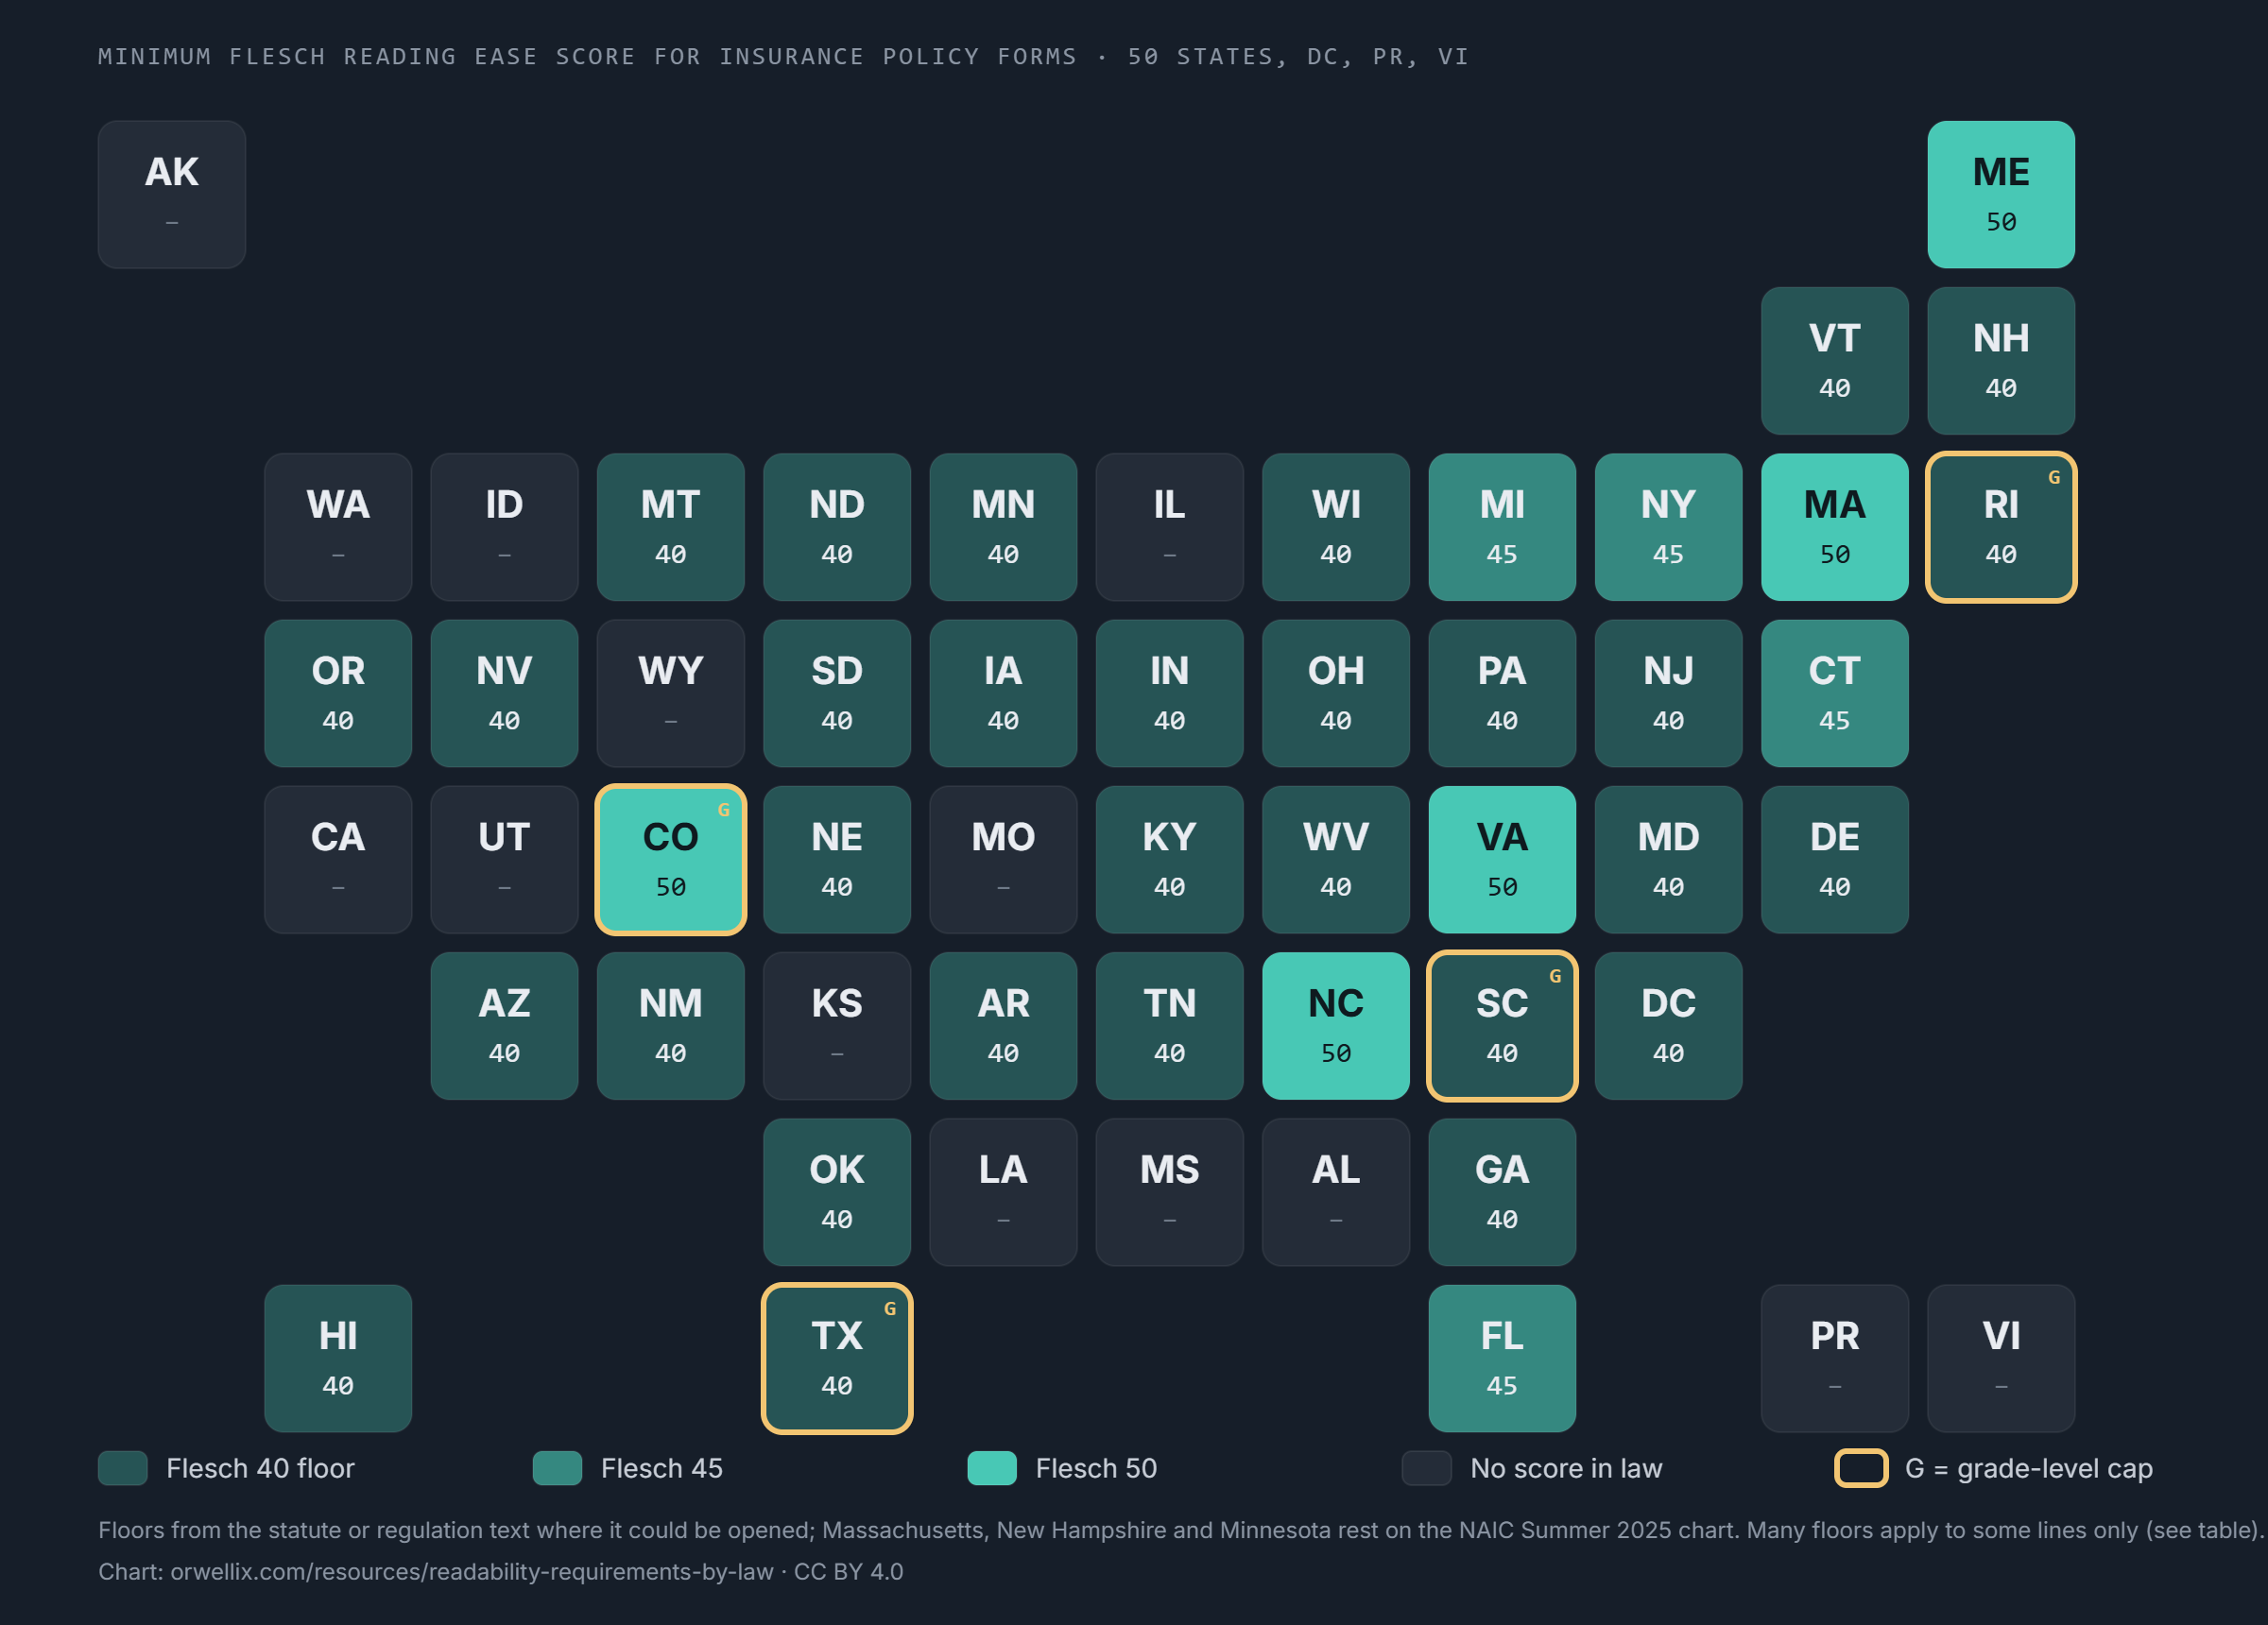
In the United States, insurance policies are the one kind of document for which a readability score is written into law: 39 of 53 jurisdictions set a Flesch Reading Ease floor, 40 in most of them, 45 in 4 and 50 in 5, and 4 states add a grade-level cap. Outside insurance, the only US law we found that names a formula is New York's 2023 ballot-proposal rule, an eighth-grade Automated Readability Index. Federal law sets standards rather than scores: "plain writing", "clearly and conspicuously", "language understandable to the subject". The one federal document that states a grade level is FDA's non-binding suggestion of a sixth-to-eighth-grade level for medication leaflets. Outside the US, no statute or regulation we opened sets a score at all: the UK, EU, Canada, Australia, New Zealand and South Africa write standards such as "plain and intelligible language" and "clear, concise and effective", and the few numbers live in style guides. Every row below quotes the law's own words and links to the text that was opened.
Each one is computed from the tables on this page, which in turn come from the statutes.
39 of 53US jurisdictions with a numeric readability floor for insurance policy forms
40The NAIC model floor since 1978, which on Flesch's own scale is still 'difficult', college-level prose
4States with a grade-level cap: Colorado, Rhode Island, South Carolina, Texas
1US law outside insurance that names a formula: New York ballot proposals, ARI grade 8 or lower
Three patterns run through the tables. First, almost every numeric rule is the same rule: the NAIC's 1978 model act wrote Flesch's 1948 computation into statute with a floor of 40, and the states copied it, sometimes raising the number, sometimes extending it from life and health forms to homeowners and auto policies[1]. Second, nearly every one of those statutes gives the regulator discretion to accept a lower score, or "an equivalent score on any other comparable test", so the floor is softer than it reads. Third, outside insurance, lawmakers who looked at readability formulas mostly declined to use them: the SEC's 1998 handbook says a formula "takes no account of the content" and that one rates Einstein at fifth grade[93], Connecticut's contract law offers word and syllable counts instead[96], and the Plain Writing Act sets a standard with no number and no judicial review[60].
02
US insurance policies
Fifty-threejurisdictions,oneformula,threefloors.
The map shows the minimum Flesch Reading Ease score each jurisdiction writes into its insurance code. The table under it gives the scope, the citation, whether the regulator can accept a lower score, and whether we read the statute itself or only the NAIC chart.
Minimum Flesch Reading Ease for insurance policy forms
39 jurisdictions with a floor; 4 at 45, 5 at 50; 4 with a grade cap
Tiles show the floor that applies to the widest line of business in that jurisdiction. Scopes differ: Delaware and Pennsylvania score auto policies only, Iowa and Vermont credit insurance, Maryland health forms. Open the table for each one.
US insurance policy readability rules by jurisdiction
Grade cap
Applies to
Lower score allowed?
Citation
Colorado
50
Flesch-Kincaid grade 10 or lower
Non-commercial auto (10-4-633.5); health benefit, limited benefit, dental and long-term care plans (10-16-107.3); Medicare supplement 40 by regulation (chart)
Not stated
C.R.S. 10-4-633.5; C.R.S. 10-16-107.3
Maine
50
—
All lines
Yes (2443)
24-A M.R.S. 2441
Massachusetts
50
—
All lines; credit disclosures and Medicare supplement by regulation
Not stated
M.G.L. c. 175, 2B; 211 CMR 71, 143
North Carolina
50
—
Personal auto, residential property, life, accident and health, HMO; group certificates (Art. 66)
No
G.S. 58-38-30, 58-38-25; 58-66-30
Virginia
50
—
Life and health forms (14VAC5-101-70, 50); credit lines (38.2-233, 38.2-3735, 40)
Yes (14VAC5-101-70 G)
14VAC5-101-70; Va. Code 38.2-233, 38.2-3735
Connecticut
45
—
All lines (health, life and disability, personal lines property and casualty)
Yes
C.G.S. 38a-297
Florida
45
—
All policy forms filed on or after 1 Oct 1983, with the model exemptions plus mortgage guaranty
Yes (the office)
Fla. Stat. 627.4145
Michigan
45
—
Policies and annuity contracts for personal, family or household purposes
Not stated
MCL 500.2236(3)
New York
45
—
Life, health, homeowners (up to four units) and personal auto forms
Yes (superintendent)
N.Y. Ins. Law 3102
Arizona
40
—
Life and disability (R20-6-213); personal auto, homeowner, dwelling and mobile-home policies (R20-6-210)
Director may authorize a lower score (R20-6-213)
A.R.S. 20-1110.01; A.A.C. R20-6-210, R20-6-213
Arkansas
40
—
Life, accident and health (23-80-206); personal lines property and casualty (23-80-306, chart only)
Yes (23-80-207)
A.C.A. 23-80-206
Delaware
40
—
Auto (18 Del. C. 2741; Reg. 605) and homeowners (Reg. 701) forms; health and life forms have a type rule only
Sub-40 forms may be approved where sentence and word length are 'sufficiently compensated for by compliance with other standards'
18 Del. C. 2741; 18 Del. Admin. Code 605, 701
District of Columbia
40
—
Life and disability forms (31-4725); auto, HMO and mental-health coverage by regulation (chart)
Yes (31-4726)
D.C. Code 31-4725
Georgia
40
—
Homeowners, tenant and personal auto policies (120-2-42); life, annuities, accident and sickness (120-2-10-.09)
Yes (120-2-10-.09 para. 10)
Ga. Comp. R. & Regs. 120-2-42, 120-2-10-.09
Hawaii
40
—
All lines (431:10-101 to 109)
Comparable test may be prescribed
HRS 431:10-104
Indiana
40
—
Life and health (27-1-26); restricting endorsements on first-party property policies (27-1-13-16, chart)
Yes (chart)
IC 27-1-26-3, 27-1-26-5
Iowa
40
—
Credit life and credit accident and health
No
IAC 191-28.14(509)
Kentucky
40
—
All personal lines policies: homeowners, dwelling fire, auto, accident and health, life
Yes
KRS 304.14-420, 304.14-440; 806 KAR 14:121
Maryland
40
—
Health insurance policies, riders and certificates (not employer groups over 1,000 or collectively bargained)
Not stated
COMAR 31.10.02.02, .03
Minnesota
40
—
All direct insurance (not group master contracts of ten or more)
Not stated
Minn. Stat. 72C.03, 72C.06, 72C.09
Montana
40
—
Life and disability (33-15-325); personal lines property and casualty (33-15-337)
Yes
MCA 33-15-325; MCA 33-15-337
Nebraska
40
—
Life and health
Yes (44-3406)
Neb. Rev. Stat. 44-3405
Nevada
40
—
Life and health, policies issued on or after 1 Jul 1983
Comparable test may be approved
NRS 687B.124
New Hampshire
40
—
Life and health
Yes
RSA 420-H:2 to 420-H:6
New Jersey
40
—
Life and health (17B:17-21); personal lines property and casualty by regulation (chart)
Yes
N.J.S.A. 17B:17-21
New Mexico
40
—
Life and health
Yes (59A-19-5, 'in his sole discretion')
NMSA 59A-19-4, 59A-19-5
North Dakota
40
—
Life (26.1-33-30); accident and health (26.1-36-14)
Yes
N.D.C.C. 26.1-33-30; 26.1-36-14
Ohio
40
—
All lines
Yes (3902.06)
R.C. 3902.04
Oklahoma
40
—
Life, accident and health forms issued on or after 1 Jan 1992
Yes (3647)
36 O.S. 3645, 3647
Oregon
40
—
Life and health
Yes (743.107)
ORS 743.106
Pennsylvania
40
—
Private passenger auto policies (31 Pa. Code ch. 64); health and life forms have an 'understandable language' standard only
Sub-40 forms may be approved where sentence and word length are 'sufficiently compensated for' by other standards
31 Pa. Code 64.12
Rhode Island
40
Flesch-Kincaid grade 8 or lower (health forms)
All individual and group health forms (230-RICR-20-30-5); credit life, accident and health, unemployment (230-RICR-20-60-1, Flesch 40)
Commissioner may authorize a higher reading level
230-RICR-20-30-5; 230-RICR-20-60-1
South Carolina
40
Flesch-Kincaid grade 7 or lower (credit insurance first-page disclosures)
Personal lines (R.69-5.1); credit life and credit accident and sickness first-page disclosures (34-29-166, 37-4-105)
Life and health; personal auto and property by commissioner's minimum (chart)
Yes (56-7-1607)
T.C.A. 56-7-1605
Texas
40
Grade 9 equivalent or easier (individual accident and health outline of coverage)
Employer health benefit plans, every page analysed (28 TAC 3.602); individual accident and health outline of coverage (28 TAC 3.3092)
Not stated
28 TAC 3.602; 28 TAC 3.3092
Vermont
40
—
Credit life and credit accident and health (Reg. I-84-1); property and casualty (Reg. I-2010-03)
Comparable test may be approved
Reg. I-84-1 s.13; Reg. I-2010-03 s.7(M)
West Virginia
40
—
Life and health
Yes (33-29-7)
W. Va. Code 33-29-5
Wisconsin
40
—
Consumer life, disability, property and casualty policies; Medicare supplement policies need 50
Yes (sub. 7)
Wis. Admin. Code Ins 6.07
Alabama
none
—
No provision
—
—
Alaska
none
—
Type size only (10-point, 120-point alphabet)
—
AS 21.51.020
California
none
—
Individual disability forms (score filed, no floor)
—
Ins. Code 10291.5; Bulletin 78-7
Idaho
none
—
No provision
—
—
Illinois
none
—
No provision
—
—
Kansas
none
—
No provision
—
—
Louisiana
none
—
No provision
—
—
Mississippi
none
—
No provision
—
—
Missouri
none
—
No provision
—
—
Puerto Rico
none
—
No provision
—
—
Utah
none
—
No provision
—
—
Virgin Islands
none
—
No provision
—
—
Washington
none
—
No provision
—
—
Wyoming
none
—
Title insurance: simple language, no score
—
W.S. 26-23-329
Showing 53 of 53 rowsStatute text opened on the official host for 18 of the 39 numeric jurisdictions, on FindLaw or Cornell LII for 18 whose official sites refuse automated access, and on the NAIC chart alone for 3.
03
US federal law and guidance
Standardseverywhere,ascorenowhere.
Every federal rule we opened that touches readability is listed, including the ones people assume contain a grade level and do not. Open a row for the law's own words.
Section 1557 nondiscrimination and language-assistance notices regulation · 2024
20-point sans serif font; English plus 15 languages Font, length or form
none
45 CFR 92.10, 92.11
Showing 27 of 27 rows'Standard' means the rule describes the writing it wants without a score, grade or count. Rows marked 'mirror' were opened on the Cornell LII copy of the US Code because uscode.house.gov returned errors.
Plain-language contract laws from 1977 onward, state plain-writing orders, and the ballot rules. Connecticut and Pennsylvania are the only ones with numbers, and New York's ballot law is the only one with a formula.
US state readability and plain-language rules outside insurance
Document
What the law requires
Formula named
Citation
California statute
State agency documents (contracts, forms, licences, regulations, manuals)
Plain, straightforward language Plain-language standard
none
Cal. Gov. Code 6219
California statute
Research subject consent (Experimental Subject's Bill of Rights)
Nontechnical terms, in a language the subject is fluent in Plain-language standard
none
Cal. Health & Safety Code 24173(c)
Connecticut statute · 1979
Consumer contracts
Average under 22 words per sentence (max 50); under 75 words per paragraph (max 150); under 1.55 syllables per word; 8-point type; 65-character lines Word or sentence counts
none (bespoke counts)
Conn. Gen. Stat. 42-152(b), (c)
Florida statute · 2025
Ballot title and summary for constitutional amendments
Summary of at most 75 words; title of at most 15 words Word or sentence counts
none
Fla. Stat. 101.161(1)
Hawaii statute · 1981
Consumer agreements under $25,000; residential leases up to five years
Clear and coherent; common and everyday words Plain-language standard
none
Haw. Rev. Stat. 487A-1
Maine statute · 1979
Consumer loan and lease agreements of supervised lenders (under $100,000)
Clear and coherent; common and everyday words Plain-language standard
none
10 M.R.S. 1121 to 1125
Minnesota statute · 1981
Consumer contracts
Clear and coherent; common and everyday words; attorney general review Plain-language standard
none
Minn. Stat. 325G.31, 325G.32, 325G.35
Minnesota executive order · 2014
Executive-branch communications
Understood the first time it is read or heard Plain-language standard
none
Minnesota Executive Order 14-07
Montana statute · 1985
Consumer contracts
Clear and coherent; readable type; contrasting ink Plain-language standard
none
Mont. Code Ann. 30-14-1103
New York statute · 1977
Residential leases and consumer agreements for personal, family or household purposes (under $250,000)
Clear and coherent; common and everyday words Plain-language standard
none
N.Y. Gen. Oblig. Law 5-702
New York statute · 2023
Statewide ballot proposals and abstracts
No higher than an 8th-grade reading level; 15-word title; 30-word summary; at most one passive sentence; no semicolons Grade level
Automated Readability Index
N.Y. Elec. Law 4-108(4)(b), (5), (7)
Oregon statute
State agency rules, forms, licences and notices
As clear and simple as possible Plain-language standard
none
ORS 183.750
Pennsylvania regulation · 1993
Consumer contracts (attorney general pre-approval checklist)
Guides: sentence average 25 words or fewer; paragraph average 60 words Word or sentence counts
none
37 Pa. Code 307.6, 307.8, Appendix B (under the Plain Language Consumer Contract Act, 73 P.S. 2201)
Texas statute · 2019
Bond election ballots
Plain language description of the purpose Plain-language standard
none
Tex. Gov't Code 1251.052(a)(1)
Washington executive order · 2005
Letters, forms, instructions and publications state agencies send to the public
Plain Talk principles: short sentences, active voice Plain-language standard
none
Washington Executive Order 05-03, Plain Talk
West Virginia statute · 1981
Written consumer agreements including residential rentals
Clear and coherent; readable type; contrasting ink Plain-language standard
none
W. Va. Code 46A-6-109
Showing 16 of 16 rowsNew Jersey's Plain Language Act (1980) is missing because no host would serve its text; see the limitations.
05
Outside the United States
Standardsinthestatutes,numbers onlyintheguidance.
40 rules from 13 jurisdictions and the EU. No statute or regulation we opened outside the US sets a readability score, grade or formula. The numbers that exist sit in guidance: a year 7 target in Australia's style manual, a 25-word sentence trigger on GOV.UK, a 90% user test for EU medicine leaflets, three sides of A4 for an investment KID.
Readability and plain-language rules outside the United States
Document
What the law requires
Formula named
Citation
Australia statute · 2004
Prospectuses and other disclosure documents; Product Disclosure Statements
Clear, concise and effective Plain-language standard
none
Corporations Act 2001 (Cth), s. 715A, s. 1013C(3)
Australia guidance · 2019
Prospectuses (how to meet s. 715A)
Highlight key information, plain language, as short as possible, explain technical terms Plain-language standard
none
ASIC Regulatory Guide 228 (August 2019), RG 228.19 to 228.25
Australia statute · 2010
Terms of standard-form consumer and small-business contracts
Transparent: reasonably plain language, legible, presented clearly, readily available Plain-language standard
none
Australian Consumer Law (Competition and Consumer Act 2010, Sch. 2), s. 24(3), s. 2
Australia guidance · 2022
Australian Government content (whole-of-government style guide)
Australian year 7 level (reading level 2, age 12 to 14), tied to WCAG SC 3.1.5 Grade level
none named
Australian Government Style Manual, 'Literacy and access'
Canada statute · 2018
Any bank communication seeking a person's express consent
Clear, simple and not misleading Plain-language standard
none
Bank Act, S.C. 1991, c. 46, s. 627.09
Canada regulation · 2021
Accessibility plans and feedback-process descriptions of federally regulated entities
Simple, clear and concise language Plain-language standard
none
Accessible Canada Regulations, SOR/2021-241, s. 5(1), 10(1)(a)
Canada guidance · 2022
Informed-consent information for research participants
Plain language statement of purpose, risks and benefits Plain-language standard
none
TCPS 2 (2022), Chapter 3, Article 3.2
European Union directive · 1993
Written terms in consumer contracts, all sectors
Plain, intelligible language; doubt resolved for the consumer Plain-language standard
none
Directive 93/13/EEC, Art. 5 and Art. 4(2)
European Union directive · 2011
Pre-contractual information for on-premises, off-premises and distance consumer contracts
Clear and comprehensible; legible and in plain, intelligible language Plain-language standard
Public documents of public service agencies and Crown agents
Appropriate to the audience; clear, concise and well organised Plain-language standard
none
Plain Language Act 2022 (2022 No 54), ss. 5, 9, 14
New Zealand statute · 2015
Terms of standard-form consumer contracts and small trade contracts
Transparent: reasonably plain language, legible, presented clearly, readily available Plain-language standard
none
Fair Trading Act 1986, s. 46L and s. 2
Norway statute · 2021
All communication by public bodies
Clear and correct language adapted to the target group Plain-language standard
none
Lov om språk (språklova), LOV-2021-05-21-42, § 9
Ontario statute · 2002
Any disclosure a supplier must make under the Act
Clear, comprehensible and prominent Plain-language standard
none
Consumer Protection Act, 2002, S.O. 2002, c. 30, Sched. A, s. 5(1)
Singapore guidance · 2024
All information given to customers by MAS-regulated financial institutions
Clear, relevant and timely information Plain-language standard
none
MAS Guidelines on Fair Dealing FSG-G04 (30 May 2024), Outcome 4
South Africa statute · 2008
Any notice, document or visual representation required to be given to a consumer
An ordinary consumer with average literacy and minimal experience can understand it without undue effort, judged on four factors including vocabulary and sentence structure Plain-language standard
none
Consumer Protection Act 68 of 2008, s. 22(2)
South Africa statute · 2005
Credit agreements, quotes and statements
Same four-factor statutory test as the Consumer Protection Act Plain-language standard
none
National Credit Act 34 of 2005, s. 64(2)
South Africa regulation · 2017
All communications by long-term insurers to policyholders; advertisements; claims communications
Plain language as defined: clear and easy to understand, avoids confusion, appropriate to the audience's knowledge Plain-language standard
All language used in public activities (courts, authorities, public bodies)
Cultivated, simple and comprehensible Plain-language standard
none
Språklag (2009:600), 11 §
United Kingdom statute · 2015
Core terms (price, subject matter) of consumer contracts
Transparent: plain and intelligible language, legible Plain-language standard
none
Consumer Rights Act 2015, s. 64(3)
United Kingdom statute · 2015
Every written term of a consumer contract and every written consumer notice
Transparent: plain and intelligible language, legible Plain-language standard
none
Consumer Rights Act 2015, s. 68
United Kingdom statute · 2015
Business insurance terms that contract out of the Insurance Act's protections
Clear and unambiguous as to its effect; drawn to the insured's attention Plain-language standard
none
Insurance Act 2015, s. 17(3)
United Kingdom statute · 2010
Information provided to disabled people by service providers, employers and public bodies
Accessible format where reasonable Plain-language standard
none
Equality Act 2010, s. 20(6)
United Kingdom regulation · 2023
All communications to retail customers by FCA-authorised firms (Consumer Duty)
Likely to be understood; clear, fair and not misleading Plain-language standard
none
FCA Handbook PRIN 2A.5.3R; FG22/5 para 8.35
United Kingdom regulation · 2015
Consumer credit communications and financial promotions
Plain and intelligible language Plain-language standard
none
FCA Handbook CONC 3.3.2R
United Kingdom regulation · 2008
Information and financial promotions for non-investment insurance
Clear, fair and not misleading Plain-language standard
none
FCA Handbook ICOBS 2.2.2R
United Kingdom guidance
All content published on GOV.UK
Split sentences over 25 words; no more than 5 sentences per paragraph; plain English mandatory Word or sentence counts
none
GOV.UK content guidance, 'Use clear language' (Government Digital Service)
United Kingdom (England) regulation · 2025
Information and communication with patients who have a disability, impairment or sensory loss
Needs identified, recorded, flagged, shared and met; accessible formats Plain-language standard
none
NHS England Accessible Information Standard DAPB1605 (30 June 2025)
W3C (adopted into law at Level AA only) standard · 2023
Web content (Success Criterion 3.1.5 Reading Level, Level AAA)
Lower secondary education level (about 7 to 9 years of schooling) after removing proper names and titles, or a simpler version supplied Grade level
none named
WCAG 2.2, SC 3.1.5
Showing 40 of 40 rowsQuebec's Civil Code and France's consumer code could not be opened (their official sites block automated access) and are left out rather than quoted second-hand.
06
What the floors mean
Afloorof40isafloor,notatarget.
Flesch labelled his own scale. The statutory minimums sit at the hard end of it.
40Difficult on Flesch's scale (30 to 50), College reading · used by NAIC model and most states
45Difficult on Flesch's scale (30 to 50), College reading · used by Connecticut, Florida, Michigan, New York
50Fairly difficult on Flesch's scale (50 to 60), 10th to 12th grade reading · used by Colorado (with a grade-10 cap), Maine, Massachusetts, North Carolina, Virginia (life and health forms)
Flesch's 1949 table puts 30 to 50 at "difficult", the register of academic and professional prose, and 50 to 60 at "fairly difficult", high-school reading. He set 60 as the minimum for plain English and 70 to 80 for consumer writing[1]. A policy that clears 40 can therefore be, by the formula's own author, harder than a college textbook. The statutes also measure only what the formula measures, words per sentence and syllables per word, so a form can clear the floor with short sentences of undefined terms and still fail its reader. The regulators knew this: the NAIC model excludes medical terminology and legally required language from the count, and lets the commissioner approve a lower score, which concedes that the number is a proxy.
The Readability Score Reference sets out the seven formulas, Flesch's conversion table and what the formulas miss. Orwellix's own readability analysis does not use a formula: it scores structural complexity, lexical sophistication, writing clarity and text coherence for each sentence and reports one grade level with the hard sentences marked, which is closer to what the Connecticut counts and the SEC's handbook were reaching for.
Thirty-five of the 39 numeric jurisdictions let the regulator approve a lower score or an "equivalent score on any other comparable test". North Carolina, Maryland and Michigan show no such clause in the text opened.
The clause is in the NAIC model (Sec. 7) and was copied almost verbatim.
Four states cap grade level instead of, or as well as, flooring the score: Colorado (Flesch-Kincaid grade 10 and Flesch 50), Rhode Island health forms (grade 8), South Carolina credit-insurance disclosures (grade 7) and Texas outlines of coverage (grade 9 on any approved test).[8][45][49][53]
Grade caps are the only place US law speaks in the units most writing tools report.
Sampling is written into the law: forms over 10,000 words may be scored on two 200-word samples per page. Georgia, Montana and South Carolina use 100-word samples; Texas requires the whole plan to be analysed.[15][52]
Two tools scoring the same policy can differ simply by which samples they take.
Federal consumer-finance rules reach for form, not score: the Loan Estimate must use the tested form H-24, the card table must show the APR in 16-point type, the Summary of Benefits and Coverage must fit four double-sided pages in 12-point type.[85][84][72]
A prescribed, user-tested form is a different theory of readability from a formula.
The Plain Writing Act has no enforcement: "There shall be no judicial review of compliance or noncompliance with any provision of this Act."[60]
Agencies report annually and the Center for Plain Language grades them, but no reader can sue. New Zealand's Plain Language Act 2022 says the same in its section 14.
The only numeric readability test in European health law is a performance test with readers: a medicine leaflet passes when 90% of test participants can find the information and 90% of those can show they understood it.[134]
South Africa's consumer and credit acts take a third route: a statutory test of whether an ordinary consumer with average literacy could understand the document without undue effort.
07
Method, limitations, data
Howthispagewasbuilt,andwhatitcould notreach.
Method
A rule reaches the table only after a person opened the statute, regulation or guidance that contains it, on 23 Oct 2026. The NAIC's Summer 2025 chart was used as an index to find citations, never as the source of a number where the text could be opened.
Where a state legislature's site refused automated access, the same section was opened on FindLaw or Cornell LII and the row is marked "mirror".
Federal regulations were read from the 2024 Code of Federal Regulations on govinfo.gov; statutes from the Cornell LII copy of the US Code where uscode.house.gov failed.
Each row records the kind of rule (score, grade, count, format or standard), the formula if one is named, who enforces it, and the law's own sentence.
Limitations
Massachusetts M.G.L. c. 175 s. 2B (Flesch 50) and New Hampshire RSA 420-H (Flesch 40): every official and mirror host blocked automated access, so both numbers rest on the NAIC chart.
Minnesota: the sections that define the computation were opened, but the sentence setting the minimum of 40 was not found in them; the 40 rests on the NAIC chart.
Seventeen state insurance rules were opened only on FindLaw or Cornell LII because the state host refused the connection. The quotes are verbatim from those mirrors and are marked 'mirror' in the table.
New Jersey Plain Language Act (N.J.S.A. 56:12-1 to -13): no host would serve the text; it is left out of the consumer-contract table.
Pennsylvania Plain Language Consumer Contract Act (73 P.S. 2201): the statute itself could not be opened; only the attorney general's regulations were, so the row rests on those.
HHS, OHRP and NIH guidance on consent reading levels: hhs.gov and nih.gov returned 403. Search results indicate OHRP sets no grade level; the common 6th-to-8th-grade targets are institutional policies.
FDA review practice of '6th to 8th grade reading level and a reading ease score of at least 60' appears in review memos found only as search snippets. It is not on this page.
Other state ballot-readability statutes named by Ballotpedia (North Dakota, Alabama, Michigan, Mississippi, Tennessee) were not opened.
Effective years are missing where a mirror omitted the history lines (Arkansas, Colorado, Connecticut, Hawaii, Indiana, Michigan, Nebraska, Nevada, New Jersey, New Mexico, North Carolina, Ohio, Oregon, Tennessee, West Virginia).
This page is a research compilation, not legal advice. Check the current text of the statute before filing.
Virginia (2020). 14VAC5-101-70; Va. Code 38.2-233, 38.2-3735, document: section70. law.lis.virginia.gov. OpenOpened 23 Oct 2026
Virginia (2020). 14VAC5-101-70; Va. Code 38.2-233, 38.2-3735, document: section38.2-3735. law.lis.virginia.gov. OpenOpened 23 Oct 2026
West Virginia (n.d.). W. Va. Code 33-29-5. FindLaw mirror. OpenOpened 23 Oct 2026
Wisconsin (1980). Wis. Admin. Code Ins 6.07. Cornell LII mirror. OpenOpened 23 Oct 2026
United States (2010). Plain Writing Act of 2010, Pub. L. 111-274, 5 U.S.C. 301 note. govinfo.gov. OpenOpened 23 Oct 2026
United States (2011). OMB Memorandum M-11-15 (13 Apr 2011). obamawhitehouse.archives.gov. OpenOpened 23 Oct 2026
United States (1993). Executive Order 12866, sec. 1(b)(12). archives.gov. OpenOpened 23 Oct 2026
United States (1996). Executive Order 12988, sec. 3(a), 3(b)(2). govinfo.gov. OpenOpened 23 Oct 2026
United States (2011). Executive Order 13563, sec. 1(a). obamawhitehouse.archives.gov. OpenOpened 23 Oct 2026
United States (2012). H.R. 3786, Plain Regulations Act of 2012 (112th Congress). govinfo.gov. OpenOpened 23 Oct 2026
United States (2018). 45 CFR 46.116(a)(3), (a)(5)(i). govinfo.gov. OpenOpened 23 Oct 2026
United States (1981). 21 CFR 50.20. govinfo.gov. OpenOpened 23 Oct 2026
United States (2006). FDA Guidance: Useful Written Consumer Medication Information (July 2006), 'Comprehensible to Consumers'. fda.gov. OpenOpened 23 Oct 2026
United States (1998). 21 CFR 208.20(a)(1), (a)(4). govinfo.gov. OpenOpened 23 Oct 2026
United States (2021). 42 CFR 422.2267(a)(1); CMS Medicare Communications and Marketing Guidelines (2018, 2022), document: CFR-2024-title42-vol3-sec422-2267. govinfo.gov. OpenOpened 23 Oct 2026
United States (2021). 42 CFR 422.2267(a)(1); CMS Medicare Communications and Marketing Guidelines (2018, 2022), document: medicare-communications-and-marketing-guidelines-3-16-2022. cms.gov. OpenOpened 23 Oct 2026
United States (2010). 45 CFR 147.200(a)(3)(i); 42 U.S.C. 300gg-15(b), document: CFR-2024-title45-vol2-sec147-200. govinfo.gov. OpenOpened 23 Oct 2026
United States (2010). 45 CFR 147.200(a)(3)(i); 42 U.S.C. 300gg-15(b), document: 300gg-15. Cornell LII mirror. OpenOpened 23 Oct 2026
United States (2000). 45 CFR 164.520(b)(1). govinfo.gov. OpenOpened 23 Oct 2026
United States (2016). 42 CFR 438.10(c)(1), (d)(6). govinfo.gov. OpenOpened 23 Oct 2026
United States (2012). 42 CFR 435.905(b). govinfo.gov. OpenOpened 23 Oct 2026
United States (2010). 42 U.S.C. 18031(e)(3)(B); 45 CFR 155.20, document: CFR-2024-title45-vol2-sec155-20. govinfo.gov. OpenOpened 23 Oct 2026
United States (2010). 42 U.S.C. 18031(e)(3)(B); 45 CFR 155.20, document: 42/18031. Cornell LII mirror. OpenOpened 23 Oct 2026
United States (2024). 45 CFR 92.10, 92.11, document: CFR-2024-title45-vol1-sec92-10. govinfo.gov. OpenOpened 23 Oct 2026
United States (2024). 45 CFR 92.10, 92.11, document: CFR-2024-title45-vol1-sec92-11. govinfo.gov. OpenOpened 23 Oct 2026
United States (1968). 15 U.S.C. 1632(a), (c), (d). Cornell LII mirror. OpenOpened 23 Oct 2026
United States (2011). 12 CFR 1026.5(a); 12 CFR 1026.17(a)(1), document: CFR-2024-title12-vol9-sec1026-5. govinfo.gov. OpenOpened 23 Oct 2026
United States (2011). 12 CFR 1026.5(a); 12 CFR 1026.17(a)(1), document: CFR-2024-title12-vol9-sec1026-17. govinfo.gov. OpenOpened 23 Oct 2026
United States (2011). 12 CFR 1026.60(a)(2), (b)(1). govinfo.gov. OpenOpened 23 Oct 2026
United States (2013). 12 CFR 1026.37(o); Dodd-Frank sec. 1032, 12 U.S.C. 5532, document: CFR-2024-title12-vol9-sec1026-37. govinfo.gov. OpenOpened 23 Oct 2026
United States (2013). 12 CFR 1026.37(o); Dodd-Frank sec. 1032, 12 U.S.C. 5532, document: 12/5532. Cornell LII mirror. OpenOpened 23 Oct 2026
United States (2011). 12 CFR 1030.3(a). govinfo.gov. OpenOpened 23 Oct 2026
United States (2000). 16 CFR 313.3(b) (FTC); 12 CFR 1016.3(b) (CFPB Regulation P), document: CFR-2024-title16-vol1-sec313-3. govinfo.gov. OpenOpened 23 Oct 2026
United States (2000). 16 CFR 313.3(b) (FTC); 12 CFR 1016.3(b) (CFPB Regulation P), document: CFR-2024-title12-vol8-sec1016-3. govinfo.gov. OpenOpened 23 Oct 2026
United States (1974). 29 U.S.C. 1022(a); 29 CFR 2520.102-2, document: CFR-2024-title29-vol9-sec2520-102-2. govinfo.gov. OpenOpened 23 Oct 2026
United States (1974). 29 U.S.C. 1022(a); 29 CFR 2520.102-2, document: 29/1022. Cornell LII mirror. OpenOpened 23 Oct 2026
United States (1998). 17 CFR 230.421(b), (d); SEC Plain English Handbook (1998), ch. 9, document: CFR-2024-title17-vol3-sec230-421. govinfo.gov. OpenOpened 23 Oct 2026
United States (1998). 17 CFR 230.421(b), (d); SEC Plain English Handbook (1998), ch. 9, document: handbook. sec.gov. OpenOpened 23 Oct 2026
United States (2013). FTC, .com Disclosures (March 2013). ftc.gov. OpenOpened 23 Oct 2026
New York (1977). N.Y. Gen. Oblig. Law 5-702. nysenate.gov. OpenOpened 23 Oct 2026
Connecticut (1979). Conn. Gen. Stat. 42-152(b), (c). FindLaw mirror. OpenOpened 23 Oct 2026
United States (2002). 52 U.S.C. 21081. Cornell LII mirror. OpenOpened 23 Oct 2026
United Kingdom (2015). Consumer Rights Act 2015, s. 64(3). legislation.gov.uk. OpenOpened 23 Oct 2026
United Kingdom (2015). Consumer Rights Act 2015, s. 68. legislation.gov.uk. OpenOpened 23 Oct 2026
United Kingdom (2015). Insurance Act 2015, s. 17(3). legislation.gov.uk. OpenOpened 23 Oct 2026
United Kingdom (2010). Equality Act 2010, s. 20(6). legislation.gov.uk. OpenOpened 23 Oct 2026
United Kingdom (2023). FCA Handbook PRIN 2A.5.3R; FG22/5 para 8.35, document: 2A/5. handbook.fca.org.uk. OpenOpened 23 Oct 2026
United Kingdom (2023). FCA Handbook PRIN 2A.5.3R; FG22/5 para 8.35, document: fg22-5. fca.org.uk. OpenOpened 23 Oct 2026
United Kingdom (2015). FCA Handbook CONC 3.3.2R. handbook.fca.org.uk. OpenOpened 23 Oct 2026
United Kingdom (2008). FCA Handbook ICOBS 2.2.2R. handbook.fca.org.uk. OpenOpened 23 Oct 2026
United Kingdom (n.d.). GOV.UK content guidance, 'Use clear language' (Government Digital Service). guidance.publishing.service.gov.uk. OpenOpened 23 Oct 2026
United Kingdom (England) (2025). NHS England Accessible Information Standard DAPB1605 (30 June 2025). england.nhs.uk. OpenOpened 23 Oct 2026
European Union (1993). Directive 93/13/EEC, Art. 5 and Art. 4(2). eur-lex.europa.eu. OpenOpened 23 Oct 2026
European Union (2011). Directive 2011/83/EU, Arts. 5(1), 6(1), 7(1), 8(1). eur-lex.europa.eu. OpenOpened 23 Oct 2026
European Union (2016). Regulation (EU) 2016/679, Art. 12(1); Recital 58. eur-lex.europa.eu. OpenOpened 23 Oct 2026
European Union (2014). Regulation (EU) No 1286/2014, Art. 6(4). eur-lex.europa.eu. OpenOpened 23 Oct 2026
European Union (2009). Directive 2009/65/EC, Art. 78(5). eur-lex.europa.eu. OpenOpened 23 Oct 2026
European Union (2014). Directive 2014/65/EU, Art. 24(3), 24(5). eur-lex.europa.eu. OpenOpened 23 Oct 2026
European Union (2016). Directive (EU) 2016/97, Arts. 17(2), 20(4), 20(7). eur-lex.europa.eu. OpenOpened 23 Oct 2026
European Union (2023). Directive (EU) 2023/2225, Arts. 8(3), 10(1), 11(1), 21(1). eur-lex.europa.eu. OpenOpened 23 Oct 2026
European Union (2019). Directive (EU) 2019/882, Art. 4 and Annex I. eur-lex.europa.eu. OpenOpened 23 Oct 2026
European Union (2014). Regulation (EU) No 536/2014, Art. 29(2). eur-lex.europa.eu. OpenOpened 23 Oct 2026
European Union (2009). European Commission, Guideline on the readability of the labelling and package leaflet (Rev. 1, 2009), under Directive 2001/83/EC Art. 59(3). health.ec.europa.eu. OpenOpened 23 Oct 2026
Canada (2018). Bank Act, S.C. 1991, c. 46, s. 627.09. laws-lois.justice.gc.ca. OpenOpened 23 Oct 2026
Canada (2021). Accessible Canada Regulations, SOR/2021-241, s. 5(1), 10(1)(a). laws-lois.justice.gc.ca. OpenOpened 23 Oct 2026
Ontario (2002). Consumer Protection Act, 2002, S.O. 2002, c. 30, Sched. A, s. 5(1). ontario.ca. OpenOpened 23 Oct 2026
Australia (2004). Corporations Act 2001 (Cth), s. 715A, s. 1013C(3). legislation.gov.au. OpenOpened 23 Oct 2026
Australia (2019). ASIC Regulatory Guide 228 (August 2019), RG 228.19 to 228.25. download.asic.gov.au. OpenOpened 23 Oct 2026
Australia (2010). Australian Consumer Law (Competition and Consumer Act 2010, Sch. 2), s. 24(3), s. 2. legislation.gov.au. OpenOpened 23 Oct 2026
Australia (2022). Australian Government Style Manual, 'Literacy and access'. stylemanual.gov.au. OpenOpened 23 Oct 2026
New Zealand (2022). Plain Language Act 2022 (2022 No 54), ss. 5, 9, 14. legislation.govt.nz. OpenOpened 23 Oct 2026
New Zealand (2015). Fair Trading Act 1986, s. 46L and s. 2. legislation.govt.nz. OpenOpened 23 Oct 2026
South Africa (2008). Consumer Protection Act 68 of 2008, s. 22(2). gov.za. OpenOpened 23 Oct 2026
South Africa (2005). National Credit Act 34 of 2005, s. 64(2). gov.za. OpenOpened 23 Oct 2026
South Africa (2017). Policyholder Protection Rules (Long-term Insurance), 2017, rules 1, 10.7.1, 11.3.1, 17.8.2. gov.za. OpenOpened 23 Oct 2026
India (2024). IRDAI (Protection of Policyholders' Interests, Operations and Allied Matters of Insurers) Regulations, 2024, Reg. 9, 11, 12. irdai.gov.in. OpenOpened 23 Oct 2026
Singapore (2024). MAS Guidelines on Fair Dealing FSG-G04 (30 May 2024), Outcome 4. mas.gov.sg. OpenOpened 23 Oct 2026
Germany (2002). Bürgerliches Gesetzbuch, s. 307(1), document: bgb/ 307. gesetze-im-internet.de. OpenOpened 23 Oct 2026
Germany (2002). Bürgerliches Gesetzbuch, s. 307(1), document: englisch bgb. gesetze-im-internet.de. OpenOpened 23 Oct 2026
Sweden (2009). Språklag (2009:600), 11 §. riksdagen.se. OpenOpened 23 Oct 2026
Norway (2021). Lov om språk (språklova), LOV-2021-05-21-42, § 9. lovdata.no. OpenOpened 23 Oct 2026
W3C (adopted into law at Level AA only) (2023). WCAG 2.2, SC 3.1.5. w3.org. OpenOpened 23 Oct 2026
09
Cite and track
Citethispage.
Cite this page
APA
Orwellix. (2026). Readability Requirements by Law. Orwellix. https://orwellix.com/resources/readability-requirements-by-law
Plain
Readability Requirements by Law (Orwellix, 2026): https://orwellix.com/resources/readability-requirements-by-law
First published 24 Oct 2026. Reuse the tables and charts with attribution under CC BY 4.0.
Changelog
First edition: 53 US insurance jurisdictions from the statutes and the NAIC chart, 46 US federal and state rules outside insurance, and the international section.
10
Questions
Thequestionsthispagegetsasked.
01Is there a legal readability requirement for insurance policies?+
In the United States, yes, in 39 of 53 jurisdictions. The NAIC's 1978 model act requires a minimum Flesch Reading Ease score of 40 for life and health policy forms, and most states adopted it, often extending it to homeowners and auto policies. Connecticut, Florida, Michigan and New York require 45; Colorado, Maine, Massachusetts, North Carolina and Virginia require 50 for some lines. Colorado, Rhode Island, South Carolina and Texas add grade-level caps on the Flesch-Kincaid or a comparable scale. Outside the US we found no statute that sets a score.
02What Flesch score does my state require?+
Find your state in the insurance table on this page. The usual floor is 40, which on Flesch's own scale is still 'difficult', college-level prose. Most statutes let the commissioner approve a lower score when legally required language drags it down, and almost all accept 'an equivalent score on any other comparable test' the regulator approves.
03Does federal law set a reading level for government documents?+
No. The Plain Writing Act of 2010 requires 'clear, concise, well-organized' writing in covered documents, with no score, no judicial review and regulations excluded. Executive orders 12866, 12988 and 13563 set the same kind of standard for regulations. The one federal document we opened that states a grade level is FDA's 2006 guidance suggesting a 6th-to-8th-grade reading level for consumer medication information, and it is non-binding.
04Is there a legal reading level for informed consent forms?+
Not in the federal rules. The Common Rule (45 CFR 46.116) and FDA's 21 CFR 50.20 require 'language understandable to the subject'. The 6th-to-8th-grade targets that appear on IRB templates are institutional policies, not regulation. California's Experimental Subject's Bill of Rights requires 'nontechnical terms' in a language the subject is fluent in, again without a number.
05Which law names a readability formula other than Flesch Reading Ease?+
New York Election Law 4-108 (2023) requires statewide ballot proposals to score no higher than an eighth-grade reading level on the Automated Readability Index, with at most one passive sentence and no semicolons. Colorado and Rhode Island use the Flesch-Kincaid grade for insurance forms, South Carolina uses it for credit-insurance disclosures, and Texas accepts Flesch, Fry, Chall, Fog or Farr-Jenkins-Paterson for an outline of coverage.
06Why do most laws set a standard instead of a score?+
Because the bodies that tried scores found their limits. The SEC's 1998 Plain English Handbook says 'no formula takes into account the content of the document' and that one formula rates Einstein's theory of relativity at 5th grade. Connecticut's contract law offers an alternative: eleven objective counts, such as an average of fewer than 22 words per sentence and 1.55 syllables per word. Orwellix's readability analysis takes the other route, scoring four dimensions of each sentence rather than two counts.